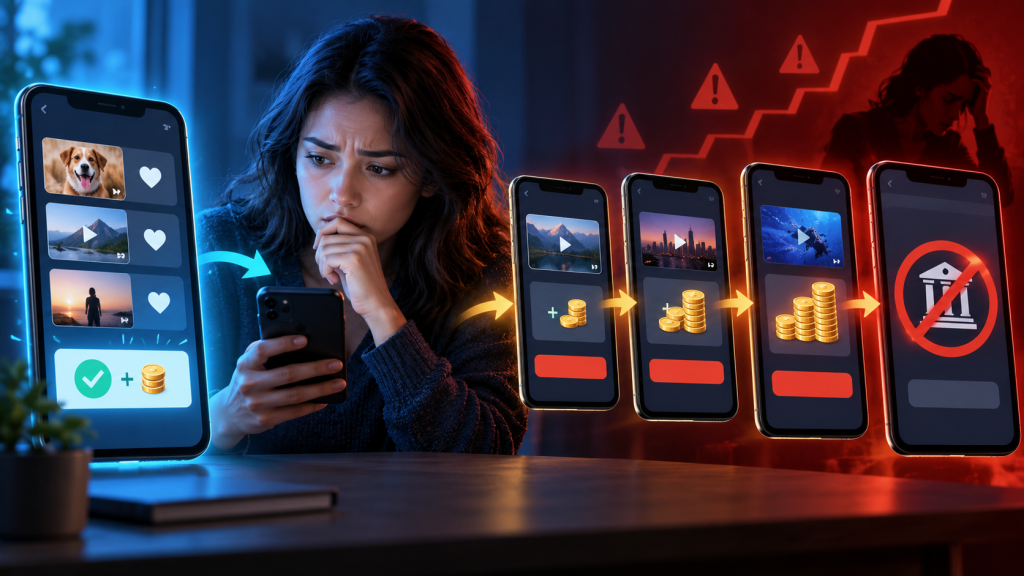
A message offers easy remote work: like a few videos, rate product images, “optimize” an app, or complete a set of clicks. The first tasks are simple. A coordinator answers quickly. A dashboard shows commissions growing. You may even receive a small payment.
That payment is not proof of a real job. In a task scam, it is often the moment the trap becomes convincing. The sender spends a small amount to build trust, then changes the rules: your account has a negative balance, a higher-value task must be completed, or a deposit is required before the displayed earnings can be withdrawn. The work was the story; your deposits are the product.
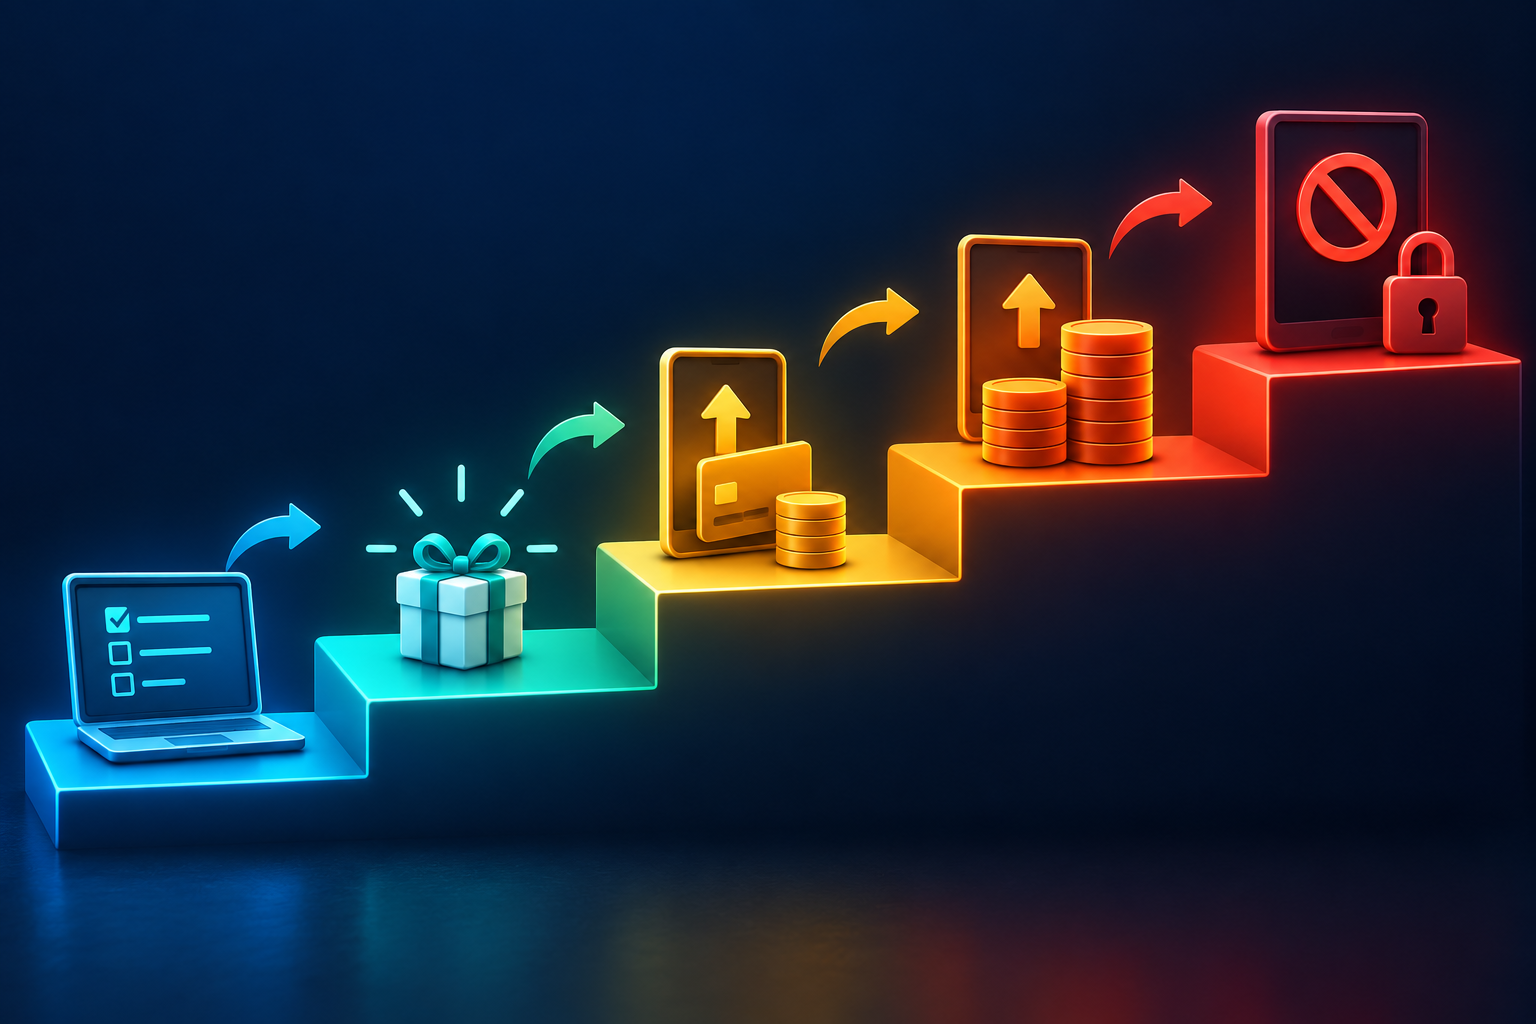
The seven-stage pattern
1. An unexpected job message
The approach often arrives by text, WhatsApp, Telegram, social media, or a vague recruiter message. It may say your number came from a job site but provide no verifiable application, job description, manager, or company email.
The sender avoids a normal interview and emphasizes flexible hours, immediate start, and unusually high earnings for repetitive activity.
2. A harmless “training” task
You are asked to like a video, rate a restaurant, click through products, or take screenshots. The task feels safe because it does not initially ask for a password or payment. It also creates a sense that you have begun working and should finish the process.
3. A small real payment
The scammer may send a modest amount through a payment app, bank transfer, or cryptocurrency. That payment can be funded by earlier victims. It proves only that someone chose to send money once. It does not establish a legal employer, a genuine business model, or an obligation to pay future “commissions.”
4. A private platform and rising balance
You receive login details for an app or website that displays tasks, levels, streaks, commissions, and a wallet balance. The numbers are controlled by the operator. A balance on a private dashboard is not money in a bank or regulated payment account.
Group chats may contain supposed workers celebrating withdrawals. Screenshots, profiles, and messages can be fabricated or managed by other members of the scheme.
5. Your money becomes part of the job
The platform says you must “recharge,” prepay an order, correct a negative balance, unlock a bundle, increase your level, or add cryptocurrency to keep working. This is the decisive change. A real wage-paying job does not require workers to deposit personal money to release ordinary earnings.
6. The loss is reframed as temporary
When you hesitate, the coordinator says one more task will recover everything. A special combination or premium order supposedly offers a larger commission. The amount required grows because previous deposits make walking away emotionally difficult.
7. Withdrawal creates another fee
The dashboard may show a large profit but demand a tax, verification payment, security deposit, liquidity fee, credit repair, or account upgrade before release. Paying the fee usually produces another condition. The displayed balance is leverage, not a recoverable asset.
Why “they paid me first” is such strong persuasion
People correctly use successful performance as evidence in ordinary business. A customer who pays an invoice becomes more credible. Task scammers exploit that habit with a deliberately limited demonstration.
The correct test is not whether one payment arrived. Ask:
- Can the employer be verified through an independently found company channel?
- Is there a real job description, contract, supervisor, payroll process, and business purpose?
- Why would productive work require the worker to send money back?
- Can earnings be withdrawn without a new deposit?
- Are the platform and recruiter connected to the company’s official domain?
A small payment cannot answer those questions.
The economics do not make sense
Legitimate marketing work can include research, content moderation, testing, and campaign management. It does not create sustainable high commissions from anonymous users repeatedly clicking a button. Paying strangers large daily returns to like public videos would be an expensive and easily abused business model.
Some schemes misuse real terms such as optimization, merchant data, product boosting, liquidity, or algorithmic ranking. Technical language does not explain where revenue comes from. Ask who pays for the service, what deliverable is produced, how quality is measured, and why the worker must finance it.
How to verify the supposed employer
- Leave the messaging conversation.
- Find the company’s official website through an independent route.
- Use the careers page or published main number to ask whether the role and recruiter exist.
- Check the sender’s email domain, not only the display name or logo.
- Search the exact job title, platform domain, recruiter name, and phrases from the message with words such as scam or complaint.
- Confirm registration or licensing only through the relevant official registry; a registration alone does not validate the job.
Do not let the recruiter provide the website, reviewer, lawyer, or “verification agent.” A fake company can build a complete set of supporting pages.
Red flags inside the task platform
- You cannot withdraw without depositing first.
- Tasks must be completed in fixed sets before any balance is released.
- A random “combination” creates a negative balance.
- Support exists only inside a chat app.
- Cryptocurrency is mandatory even though the work is ordinary marketing.
- The worker must borrow from friends to protect the account.
- The platform shows urgency, countdowns, penalties, or an expiring credit score.
- A group pressures anyone who questions the process.
- Taxes or fees are paid to a private wallet instead of handled through a documented payroll or government system.
If you received a small payment but sent nothing
Stop. Do not complete another task, return money to a different account, recruit someone else, or send a “verification deposit.” Save the messages and transaction details. Block the contact after preserving what you need for a report.
Do not assume the initial payment is safe to spend. It may be reversed, disputed, stolen, or connected to another victim. Contact the payment provider through its official app and explain that the transfer came from a suspected task scam. Follow its instructions rather than the recruiter’s refund route.
If you created an account on the platform
If you reused a password, replace it everywhere else from a trusted device. Review the email and phone number connected to the fake platform for follow-up phishing. If you installed an app outside an official store, granted a device-management profile, or allowed accessibility or remote-control access, stop using the device for sensitive accounts until it is assessed.
Do not upload more identity documents to close the account. Preserve evidence, then remove the app and permissions according to the phone platform’s official guidance.
If you deposited money
Do not send another payment to unlock the earlier one. Contact the bank, card issuer, payment app, or cryptocurrency exchange immediately through a verified channel. Explain the transfer method, destination, time, amount, and scam platform. Ask what recall, freeze, dispute, or fraud-reporting options apply. Recovery is not guaranteed, and speed can matter.
For cryptocurrency, preserve:
- wallet addresses;
- transaction hashes;
- exchange account and transfer records;
- screenshots of the platform balance and deposit instructions;
- messages, usernames, phone numbers, and website addresses;
- a timeline of every payment.
Do not send anyone your wallet recovery phrase or private key. A real exchange or law-enforcement agency does not need those secrets to view a public transaction.
If you borrowed money or involved another person
Tell the lender or person promptly and factually. Do not continue the scam in an attempt to repay them from a promised withdrawal. If you recruited someone, warn them not to deposit and share the official reporting route.
Shame helps the scammer keep the sequence private. A clear disclosure can stop another payment and improve the evidence available to banks and investigators.
Protect identity and accounts shared during recruitment
Fake recruiters may collect a résumé, passport or identity-card image, bank details, tax number, selfie, home address, or video interview before the payment demand. Write down exactly what you supplied. Change reused credentials and watch the email and phone number for targeted follow-up messages.
Contact the issuing agency or institution when a government document, bank account, or tax identifier was exposed. Ask what fraud flags, replacement, monitoring, or identity-theft report applies in your country. Do not send another copy of the document to an unsolicited “compliance team” that offers to remove it.
Why leaving becomes harder after each deposit
The platform displays the previous payments as if they are waiting just one step away. That creates a sunk-cost decision: losing the money already sent feels worse than risking a little more. The coordinator adds social pressure by praising persistence, blaming the worker for pausing, or showing other users who supposedly completed the level.
Stop evaluating the next fee in isolation. Add every deposit and ask whether any independently verified employer ever promised the balance. A larger amount shown on the screen does not improve the chance of withdrawal. It only makes the next demand feel smaller by comparison.
Take a break from the chat and tell someone you trust the full amount. An outside person is not carrying the same dashboard pressure and may see the pattern more clearly.
Report through a route you open yourself
In the United States, report to the FTC at ReportFraud.ftc.gov and the FBI’s Internet Crime Complaint Center at IC3.gov. The FBI warns that scammers also impersonate IC3 and recovery officials. Type the official address yourself; do not use a link sent by someone claiming to recover funds.
Report the account, group, and messages to the messaging platform. Other countries have national fraud and cybercrime reporting services. Provide the evidence without publishing personal documents or wallet secrets.
Expect a recovery scam
After a loss, someone may claim to be a lawyer, blockchain investigator, government official, hacker, or victim-support agent who can recover the funds for an upfront payment. They may know the exact platform and amount because the original scammers shared or sold the information.
The FBI states that IC3 does not ask victims for payment to recover funds and does not refer them to companies that charge such fees. Verify any official contact independently. Never pay a tax, bond, gas fee, or deposit to release supposedly recovered money.
How this differs from a legitimate microtask platform
Real freelance and microtask services can pay small amounts for defined work, deduct transparent platform fees, require tax information, and enforce quality rules. Those features do not guarantee a service is good, but the worker is not asked to fund an artificial account balance to get wages.
A legitimate platform should identify the contracting entity, terms, dispute process, payment method, and actual work product. It should not invent random negative balances or require cryptocurrency deposits to continue.
A one-sentence stop rule
If an online job requires you to send personal money in order to complete tasks or withdraw earnings, stop. The earlier payment, dashboard profit, supportive group, and urgent deadline do not change that rule.
For the unexpected recruitment message itself, use the 12-point scam-message checklist. If you opened or installed something from the platform, follow the suspicious-link recovery guide.